This article may contain affiliate links. Learn more on our Partner Program page.
Just days after reports of reduced iPhone 18 Pro orders, JP Morgan raised its price target for Apple stock by $20. The analysts consider the cuts to be standard adjustments and fully expect the iPhone Duo to launch. Nevertheless, they anticipate a decline in iPhone revenue for the holiday quarter.
JP Morgan has raised its price target for Apple stock from $340 to $360, according to an investor note from JP Morgan obtained by AppleInsider. At the end of July, the bank had lowered its target to $340, citing supply chain bottlenecks and rising component prices.
The reason for this new note is a report by Nikkei Asia that Apple has allegedly cut component orders for the iPhone 18 Pro by at least 15 percent compared to the original plan. JP Morgan advises investors to ignore this report.
Key Facts at a Glance
- JP Morgan raises its price target for Apple stock from $340 to $360.
- Analysts believe the reported order reductions for the iPhone 18 Pro are due to normal production adjustments.
- The bank expects to sell around 8.5 million iPhone Duos in the December quarter.
- iPhone sales are expected to decline by around 2 percent in the December quarter, while total sales are expected to increase by around 2 percent.
Cuts as an annual routine
According to JP Morgan, the report reveals nothing beyond the usual production adjustments Apple makes each year. Demand for the iPhone 18 Pro is currently slightly higher than that of the iPhone 17 Pro at the same time, albeit only just. Furthermore, last year's model continues to sell well.
The bank is nevertheless slightly lowering its expectations for the December quarter. It attributes this to the staggered launch of the iPhone generation: the base model, the iPhone 18, won't arrive until early 2027. Buyers waiting for this model are therefore absent from the current quarter.
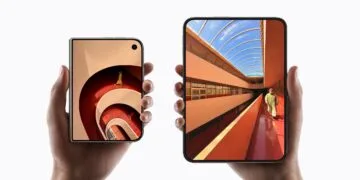
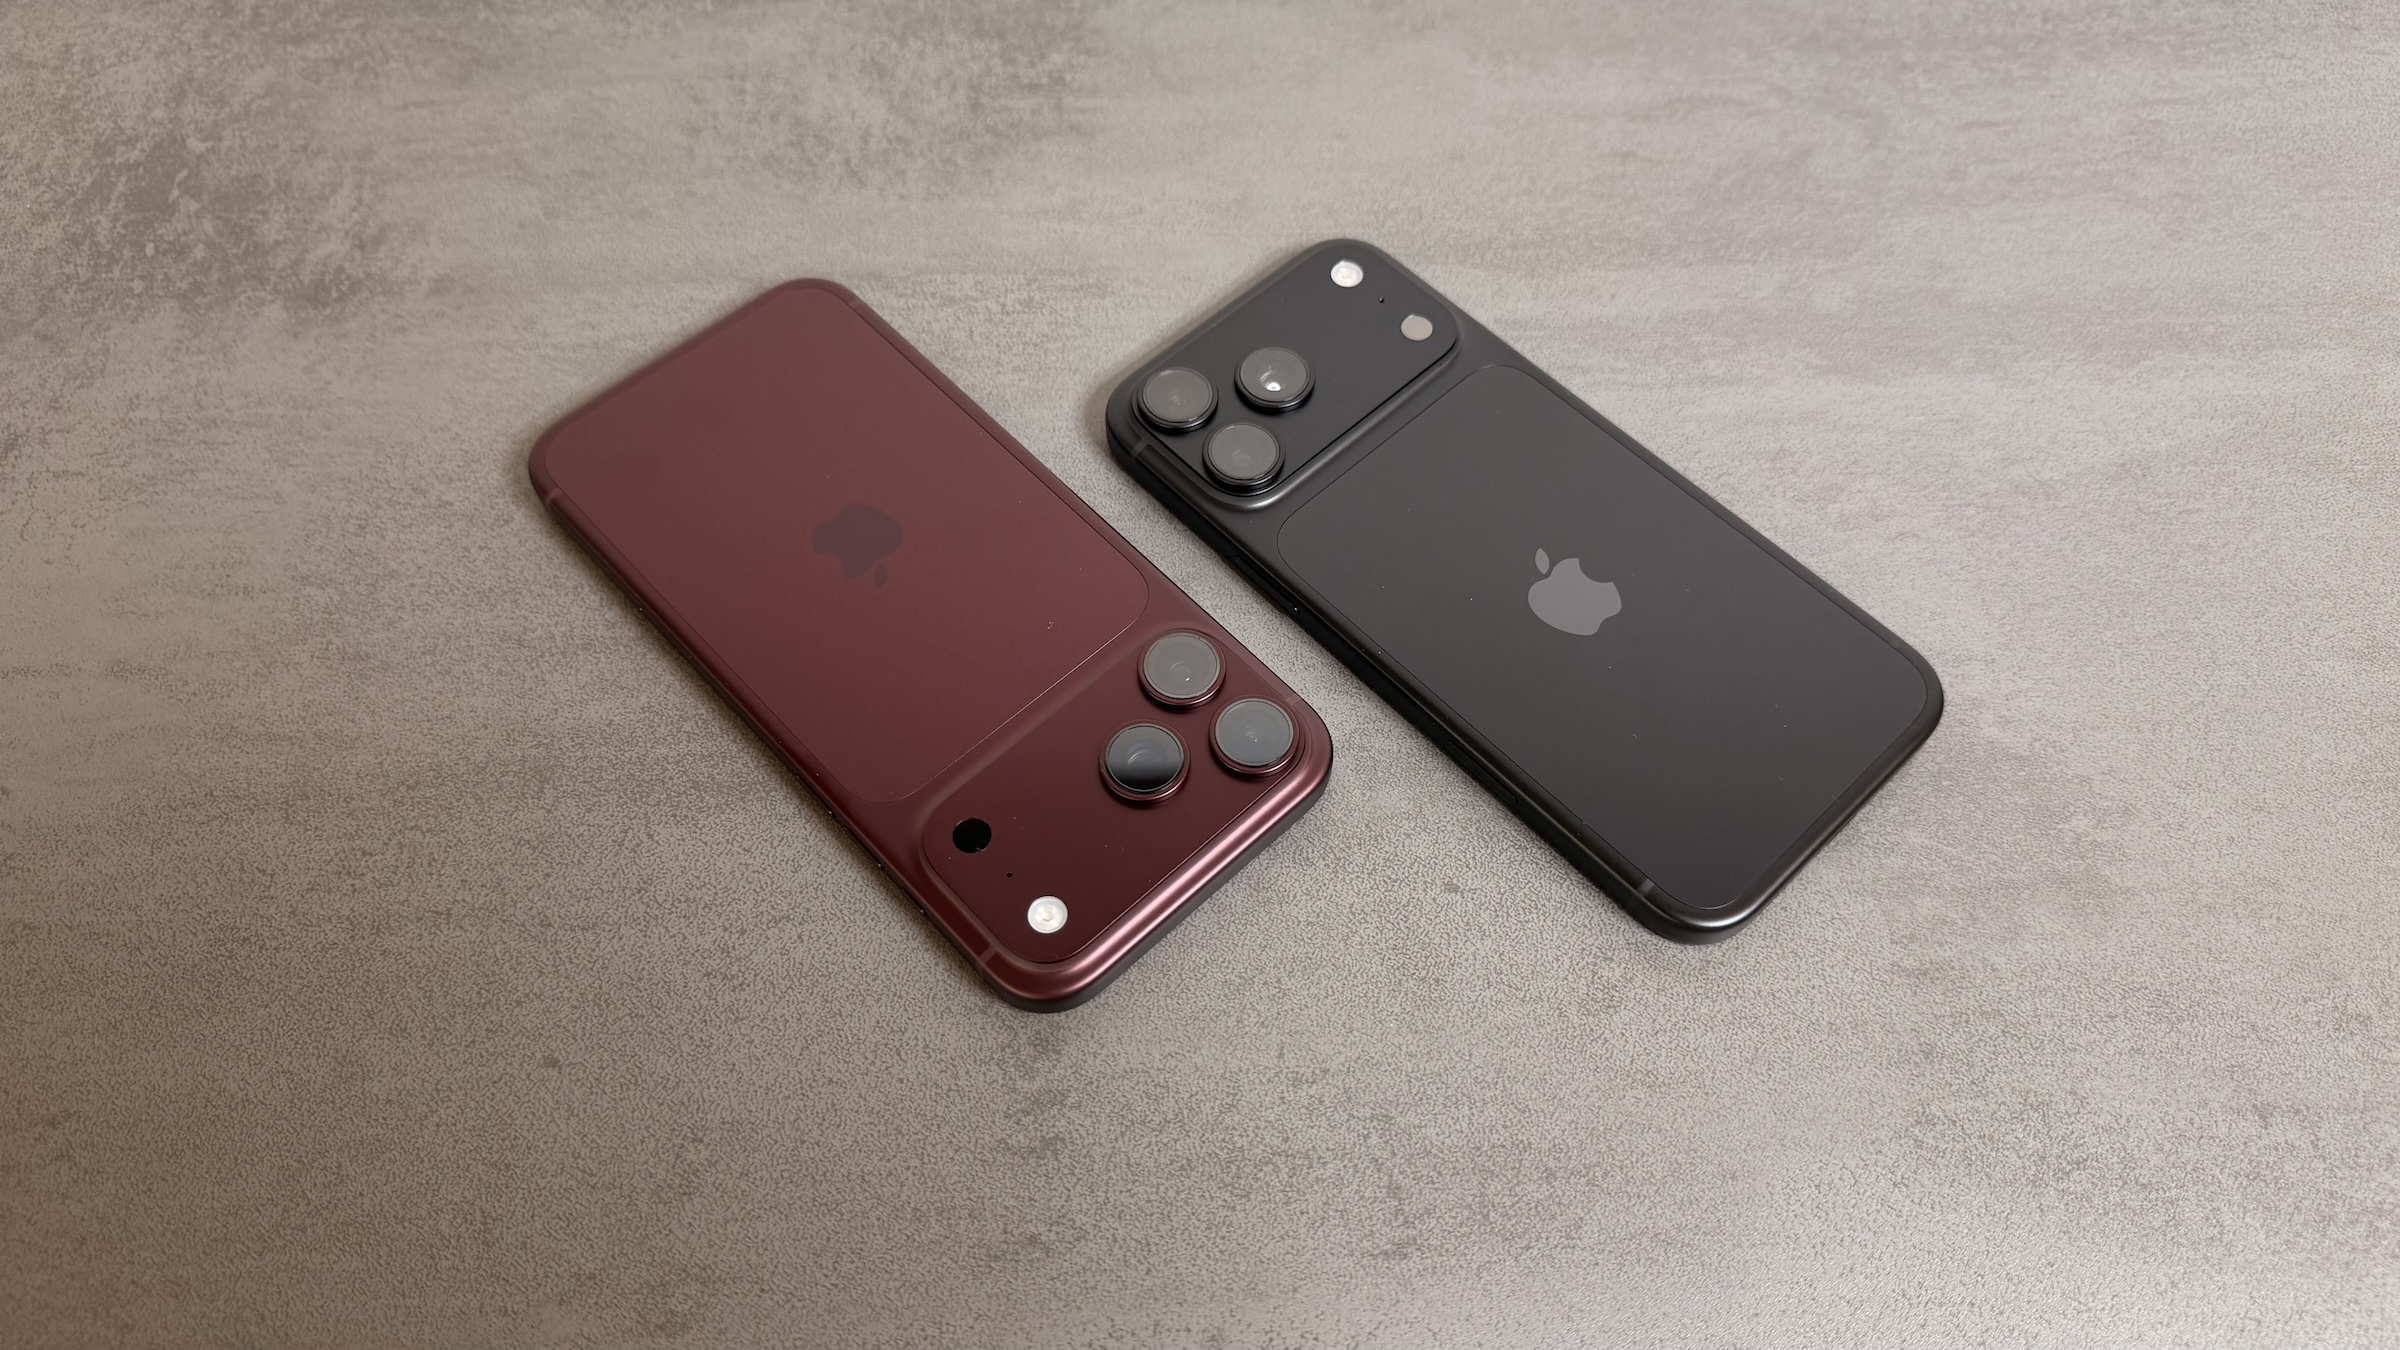
At the same time, analysts believe the split should bring additional buyers to the Pro models. The gap is expected to be filled primarily by the iPhone Duo, which will be released on October 23.
What JP Morgan expects for the next few quarters
For the September quarter, Apple's fourth fiscal quarter, analysts expect figures slightly above market expectations. They continue to cite supply chain bottlenecks as a contributing factor. Apple will release these figures on November 2nd at 11 PM German time.
The forecast for the December quarter looks like this:
| Key figure | JP Morgan's expectations |
|---|---|
| iPhone Duo | approximately 8.5 million devices sold |
| iPhone sales | approximately 2 percent below the previous year |
| Total sales | approximately 2 percent above the previous year |
The bank attributes the decline in iPhone sales to fewer devices sold due to the lack of a new entry-level model. Higher iPhone prices and the expensive iPhone Duo are expected to boost overall revenue nonetheless.
The Duo estimate is higher than other figures
With approximately 8.5 million units sold in the December quarter, JP Morgan's estimate is significantly higher than other reports. Counterpoint Research had projected around 6 million iPhone Duo units sold by the end of the year at the end of September. A supply chain source had estimated Apple's inventory target for 2026 at 6 to 8 million units.
The figures don't measure exactly the same thing: JP Morgan speaks of sales in a single quarter, Counterpoint of deliveries by the end of the year, and the supply chain source of an inventory target. Since the iPhone Duo doesn't launch until October 23, however, the timeframes largely coincide. In addition, there are reports of a yield of only around 60 percent in final assembly.
The risks from the bank's perspective
Despite the optimistic tone, JP Morgan also points out risks. A large part of these concern the global economy and its impact on demand. Added to this are local competitors in international markets who can react more quickly with price reductions, as well as tariffs that governments use to protect domestic manufacturers.
Within Apple's own sphere of influence, the bank continues to list the change at the top of the company as a risk, but acknowledges that the transition to John Ternus has been successful so far. Acquisitions are considered another risk, as they could distract management and bring costs or obligations.
The price target returns
JP Morgan's target has changed several times this year:
| Date | Course objective |
|---|---|
| January 30, 2026 | $325 |
| July 7, 2026 | 345 dollars |
| July 31, 2026 | $340 |
| October 2026 | $360 |
I consider the Duo estimate to be the truly interesting part of the note, not the price target. If Apple is indeed expected to sell around 8.5 million devices in the first sales quarter, manufacturing would have to mature significantly faster than current supply chain reports suggest. Whether this will happen will be revealed by delivery times after pre-orders begin on Friday.
Do you think 8.5 million iPhone Duo sales by the end of December are realistic – or will the limited supply slow the device down more than JP Morgan expects? Share your prediction in the comments.