This article may contain affiliate links. Learn more on our Partner Program page.
According to Loop Capital, Apple has removed 13 million iPhones from its plans for the second half of the year, and these are not expected to return. Analysts have therefore downgraded the stock. Other firms interpret the same signals quite differently.
Loop Capital downgraded Apple from "Buy" to "Hold" on October 20 and lowered its price target from 370 to 330 dollars, according to a report on the analyst note. The note was written by analyst Ananda Baruah. At its core is a changed assumption about the reduced iPhone unit numbers.
This puts Loop in the opposite direction to JP Morgan. The bank had only raised its price target to $360 on October 12th and classified the reported cuts as a routine adjustment. Clarity will only come with the quarterly figures on November 2nd.
Key Facts at a Glance
- Loop Capital downgrades Apple from "Buy" to "Hold," lowering its price target from $370 to $330.
- Apple is said to have cut its iPhone production plans for the September and December quarters by around 10 percent, a total of about 13 million devices.
- Loop expects 79 million iPhones to be sold in the December quarter, while the consensus estimate is 85 million.
- Loop expects more iPhones to be sold in 2027, but significantly less revenue.
- JP Morgan and the market researchers at Counterpoint attribute the weaker figures primarily to the staggered market launch.
What Loop now expects
Loop had previously assumed that Apple would largely make up for the reduced production volumes by 2027, because the cuts were due to shortages of memory and processors, not weak demand. However, after its own supply chain audits, Loop has revised this view.
That no longer seems to be the case.
Loop does not expect Apple to replace the 13 million iPhones that were removed from its plans for the second half of 2026. In addition, rising storage costs could put pressure on profit margins.
| Key figure | Until now | New |
|---|---|---|
| Classification | Buy | Hold |
| Course objective | $370 | 330 dollars |
| Average iPhone price, December quarter | $1,239 | $1,123 |
| Average price of iPhone, 2027 | $1,235 | $1,096 |
| iPhone production number 2027 | – | 260 million |
| iPhone revenue 2027 | $315 billion | $285 billion |
| Earnings per share 2027 | $10.11 | $9.76 |
| Normalized earnings per share | 12 dollars | 11 dollars |
The new price target is derived from normalized earnings of $11 and a price-to-earnings ratio of 30. Loop sees further long-term potential in market share and services.
An autumn with fewer new models
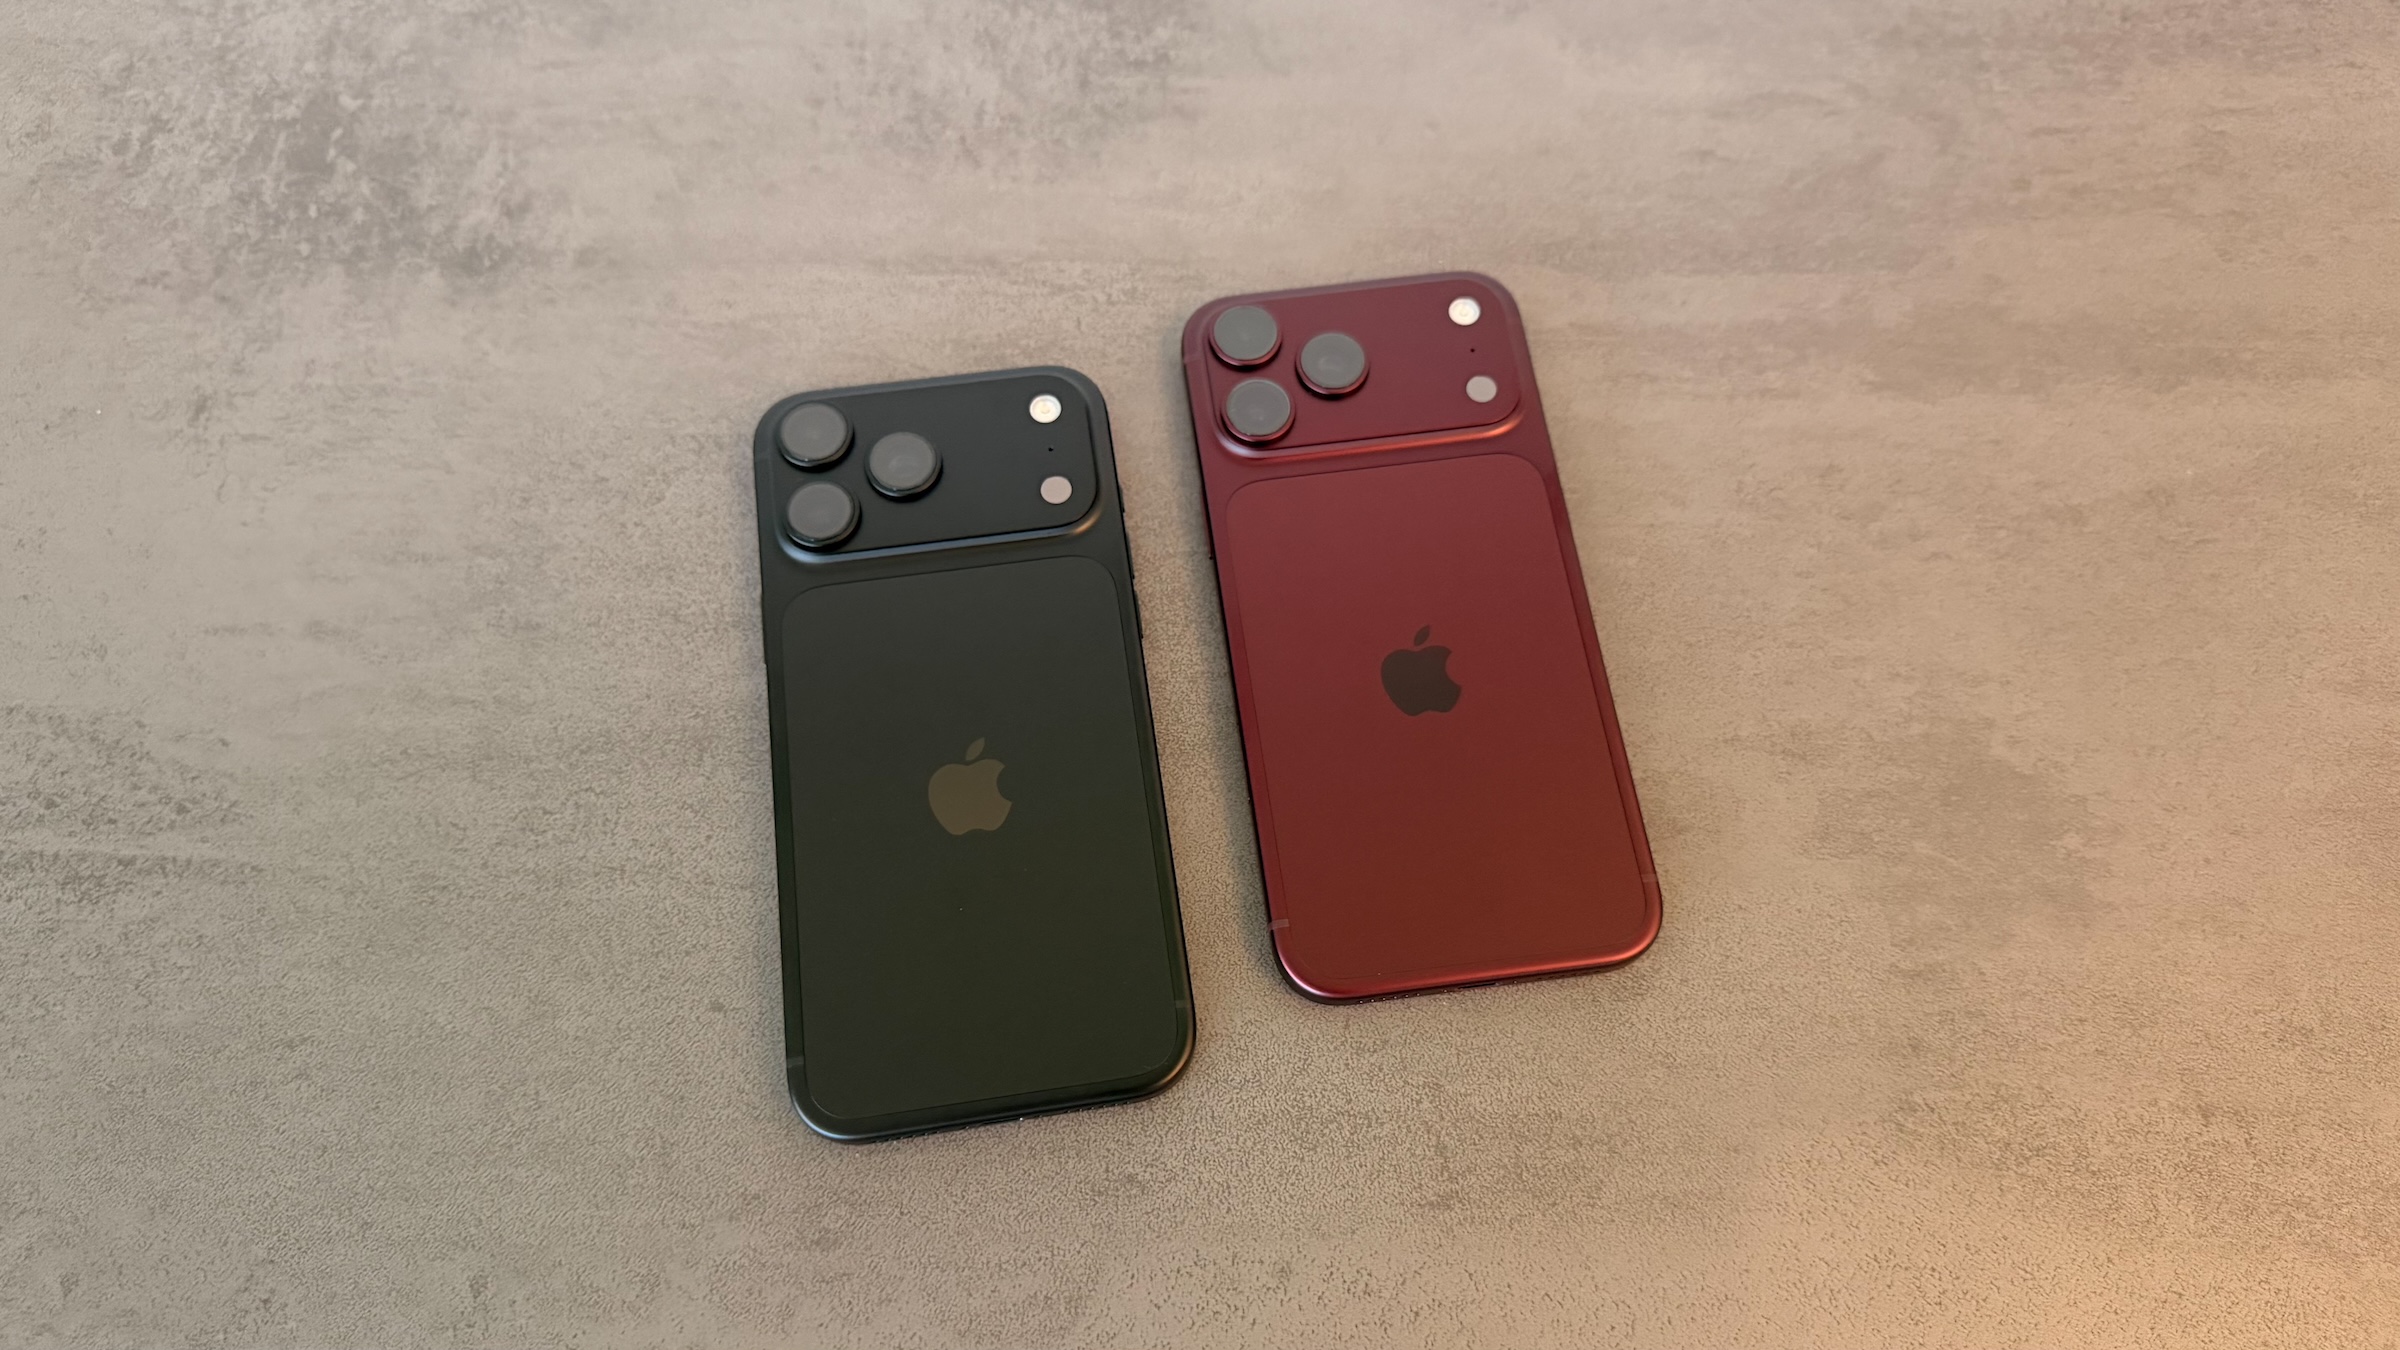
The comparison with the previous year has a catch. In 2025, the standard iPhone 17 model was released in September along with the Pro models. In 2026, only the iPhone 18 Pro and Pro Max launched in September; the iPhone Duo followed on October 23rd, and the iPhone 18 is not expected to go into production until the end of November and be released in early 2027.
With fewer new models this fall, shipments could decline without a corresponding decrease in demand. JP Morgan argued precisely this point on October 12th. Counterpoint also attributed the third-quarter decline primarily to the lack of a standard model, while Apple captured a record share of the shrinking smartphone market.
The lower average price projected for 2027 fits this interpretation. If the more affordable iPhone 18 is added in the new year, the number of units sold will increase, while the price per device will decrease.
Conflicting signals from the supply chain
The basis for all these calculations is flimsy. In early October, Nikkei Asia reported reduced component orders for the iPhone 18 Pro, citing supply chain sources but without supporting documentation. However, fewer components ordered do not necessarily mean fewer finished iPhones.
Jefferies interprets the delivery times as an indication of weaker demand. In a note dated October 2nd, wait times for the Pro Max were shorter in the UK and Germany than the previous year, but longer in Hong Kong, China, and the US. Shorter delivery times could also mean that Apple has sufficient stock.
What November 2nd can clarify
I believe the 13 million figure is the real weak point of the downgrade. Neither the supply chain data nor the analyst notes can tell how many of these are truly wasted purchases and how many buyers are simply waiting for the iPhone 18. This distinction, however, is crucial in determining whether Loop or JP Morgan is right.
The figures released on November 2nd pertain to the September quarter, and thus the first half of the period for which Loop anticipates the reduction. For iPhone buyers in this country, the change has no impact, as the standard model won't be available until the new year anyway.
Who's right – Loop with their losing buys or JP Morgan with their postponed buys? Write your prediction in the comments.