This article may contain affiliate links. Learn more on our Partner Program page.
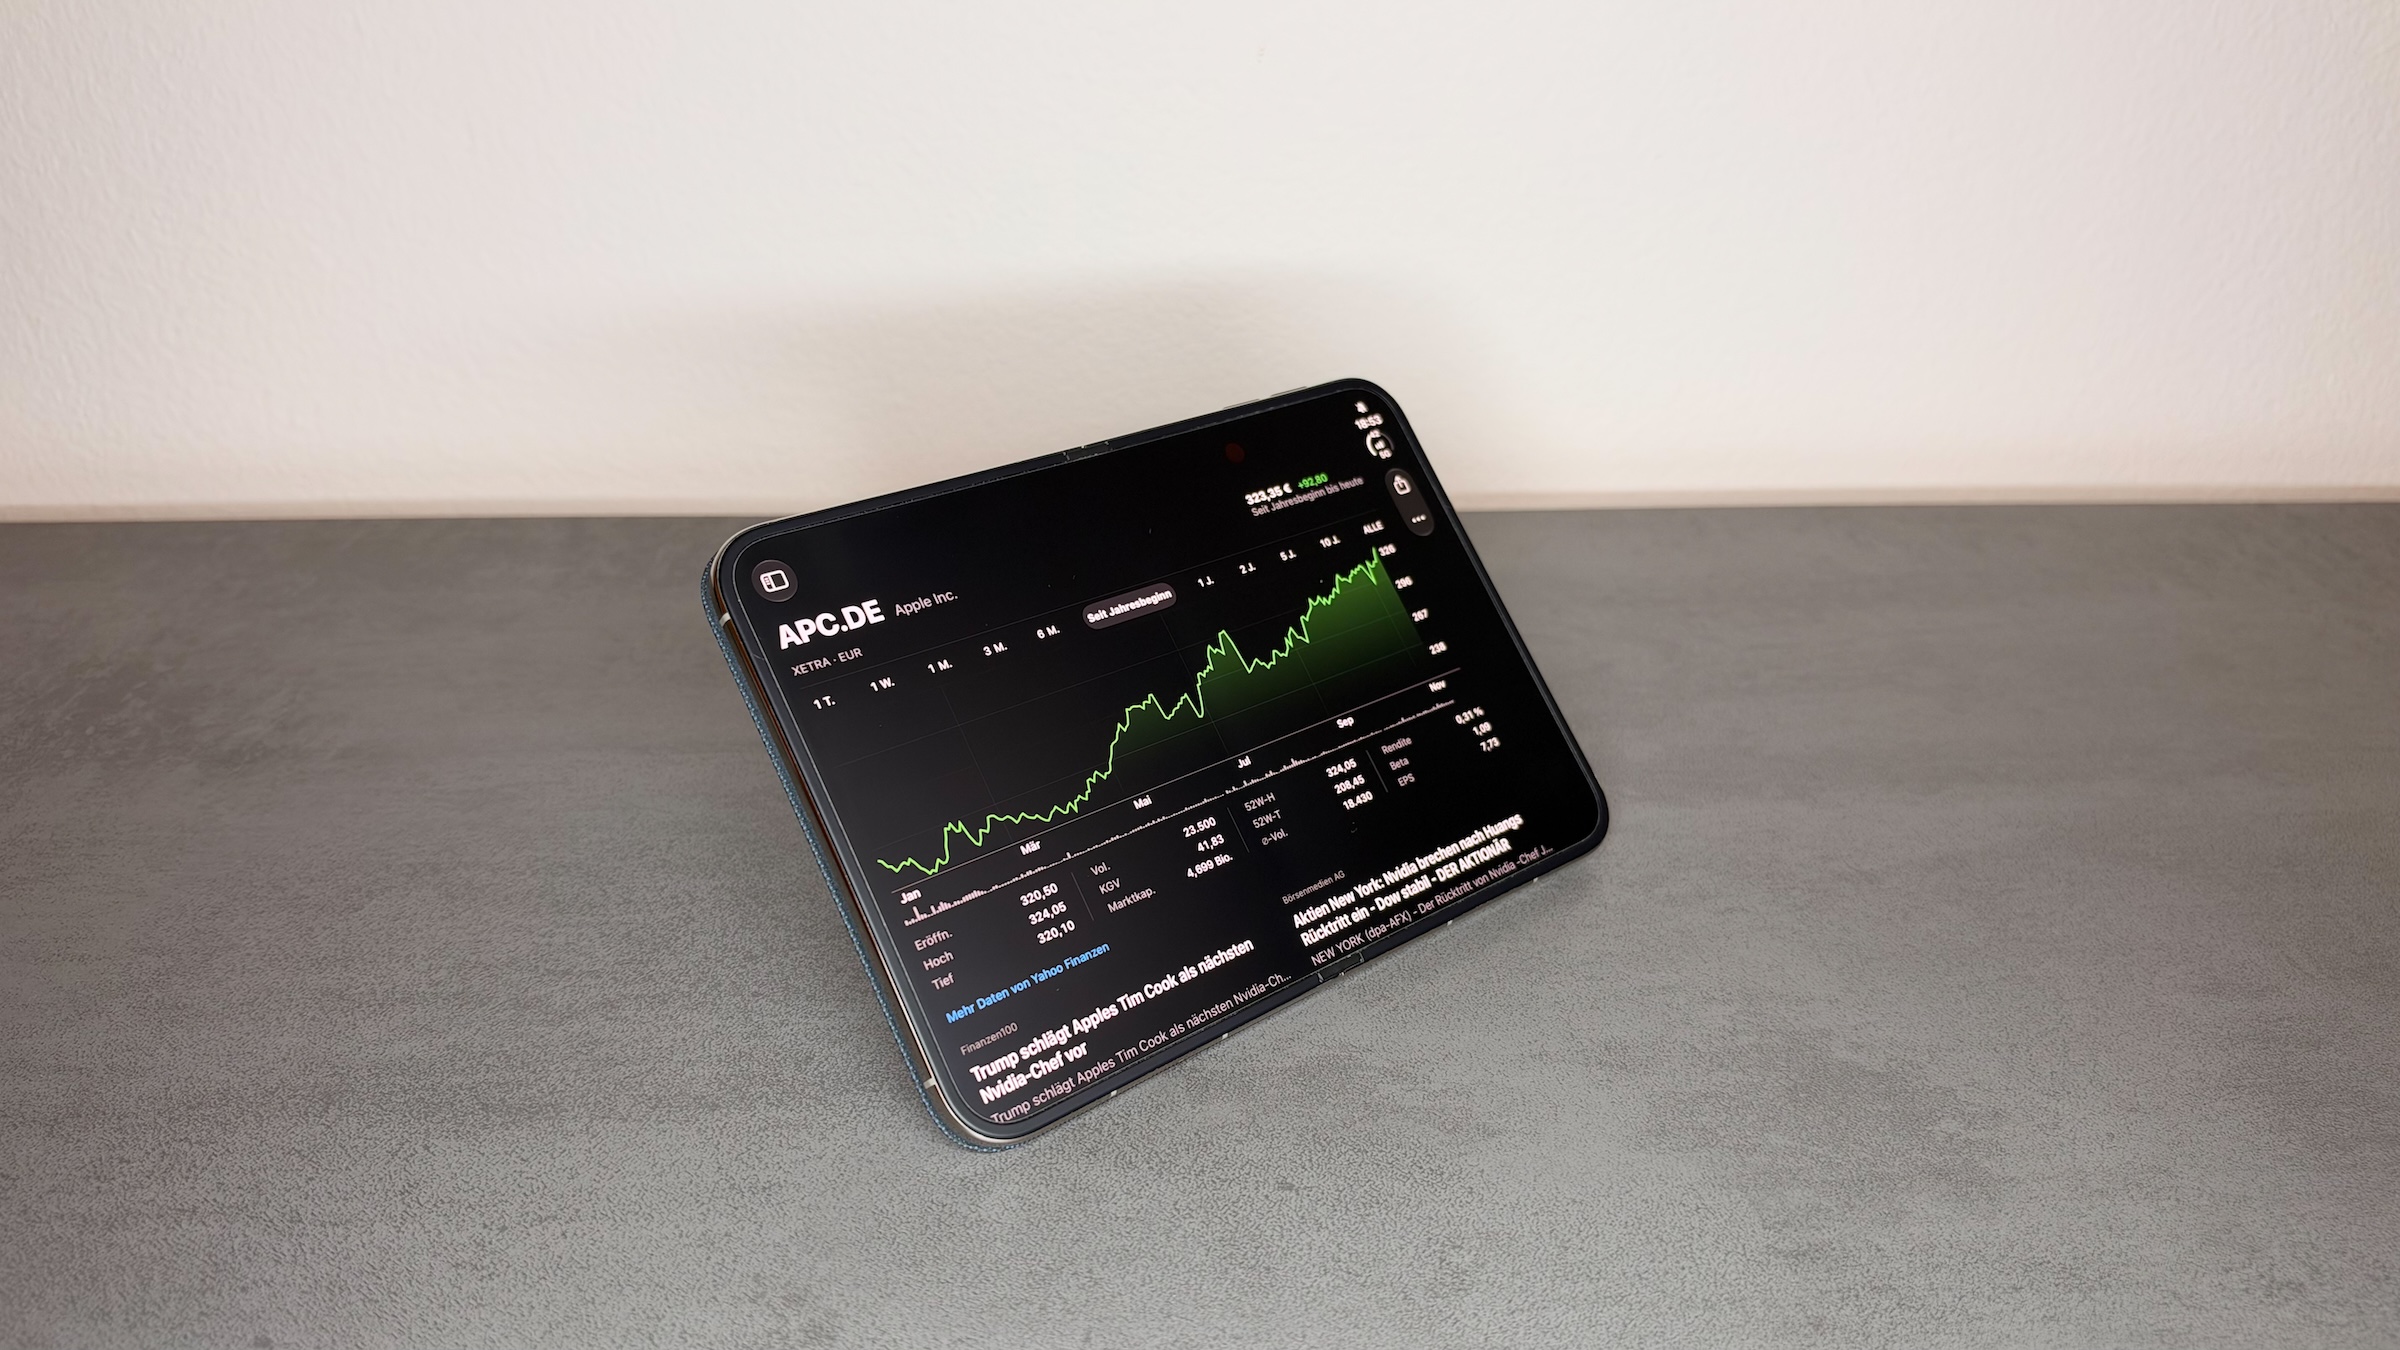
An analyst firm is betting everything on the foldable iPhone. China Renaissance has upgraded Apple stock back to "buy" and raised its price target by more than half to $425. The reasoning is based on a device that has only been on the market for three weeks.
Analysts Jack Zhou and Lemuel Lin of China Renaissance upgraded Apple stock from „Hold“ to „Buy“ on November 11 and raised their price target from $280 to $425. This is currently the highest price target on Wall Street.
The iPhone Duo, which has been on the market since October 23, is the central focus of the explanation. Analysts see it as the trigger for a new upgrade cycle.
Key Takeaways
- China Renaissance upgrades Apple stock from „Hold“ to „Buy“ and raises its price target from $280 to $425.
- Compared to the closing price of $348.51 on November 10, this represents a potential increase of almost 22 percent.
- Analysts expect the iPhone Duo to prompt many users to switch sooner.
- Just in August, the same firm had downgraded the stock due to weaker services growth and higher storage costs.
- Reliable sales figures for the duo are not yet available.
What's behind the upgrade
Zhou and Lin expect the iPhone Duo to change how customers use their iPhones and prompt existing owners to switch sooner. They cite the larger foldable display, multitasking capabilities, and Siri AI as reasons for this.
Analysts believe the duo will create a new growth platform that offsets the pressure on margins. This pressure stems from higher storage costs and slower growth in services.
A complete turnaround within three months
In August, Zhou had downgraded the stock to „Hold.“ At that time, Apple's outlook for the fourth quarter indicated services growth of only around 10 percent, compounded by rising storage costs and a weaker mobile gaming business.
Concerns about margins and services haven't disappeared, according to the new assessment. Analysts simply believe they are less significant than what the duo could deliver in the long run. The price increase from $280 to $425 represents a rise of approximately 52 percent.
How the goal compares
The other houses are significantly lower. The most recent assessments since the quarterly figures were released on November 2nd:
| Date | House | Classification | Course objective |
|---|---|---|---|
| November 11 | China Renaissance | Buy | $425 |
| November 10th | Evercore ISI | Outperform | $380 |
| November 4th | amber | Buy | $380 |
| November 3 | Argus Research | Buy | $400 |
| November 3 | JPMorgan | Overweight | 355 dollars |
| November 3 | UBS | Neutral | $340 |
| November 3 | Barclays | Underweight | 261 dollars |
The difference between the highest and lowest targets on this list is $164. Barclays thus sees the stock trading at around 25 percent lower than its price on November 10, while China Renaissance is projected to trade at almost 22 percent higher.
A bet on numbers that don't yet exist
I consider the reasoning bold because it lacks a solid foundation. The duo has only been on the market for three weeks, and Apple hasn't reported iPhone unit sales for years. Whether the device triggers an upgrade cycle can only be determined at the earliest with the Christmas quarter figures, and even then, only based on total iPhone sales.
Two additional factors argue against a rapid effect. Apple has acknowledged a persistent supply shortage of the Duo, and there were issues with the internal display in a small number of devices. Anyone relying on a supercycle needs a device that is readily available in large quantities.
Do you think the iPhone Duo will prompt enough buyers to switch earlier to noticeably change Apple's numbers? Let us know in the comments if it made you switch.